From Rent to Own: Exploring the Shift in Homeownership Trends
 Moureen Nungari
For many Kenyans, owning a home is still one of the biggest financial goals. The challenge is often not the desire to own property but having enough money for the deposit and being able to manage the monthly payments.
As property prices and the cost of living continue to put pressure on household budgets, a different approach to buying property is gaining attention: rent-to-own and flexible payment plans.
Instead of waiting until they have enough cash to buy a property outright, more buyers are looking for ways to spread the cost of ownership over time.
Traditional property purchases usually require a substantial upfront payment, followed by either cash payments or mortgage financing. For a buyer earning a regular income, raising a large deposit can be difficult even when the monthly cost of owning the property may be manageable.
This is where flexible payment structures can make a difference. Some private developers offer buyers the option of paying a deposit and completing the balance through monthly or quarterly instalments during the construction period or over an agreed payment period.
While these arrangements are not always technically “rent-to-own,” they address the same problem: making property ownership possible without requiring the buyer to have the entire purchase price available immediately.
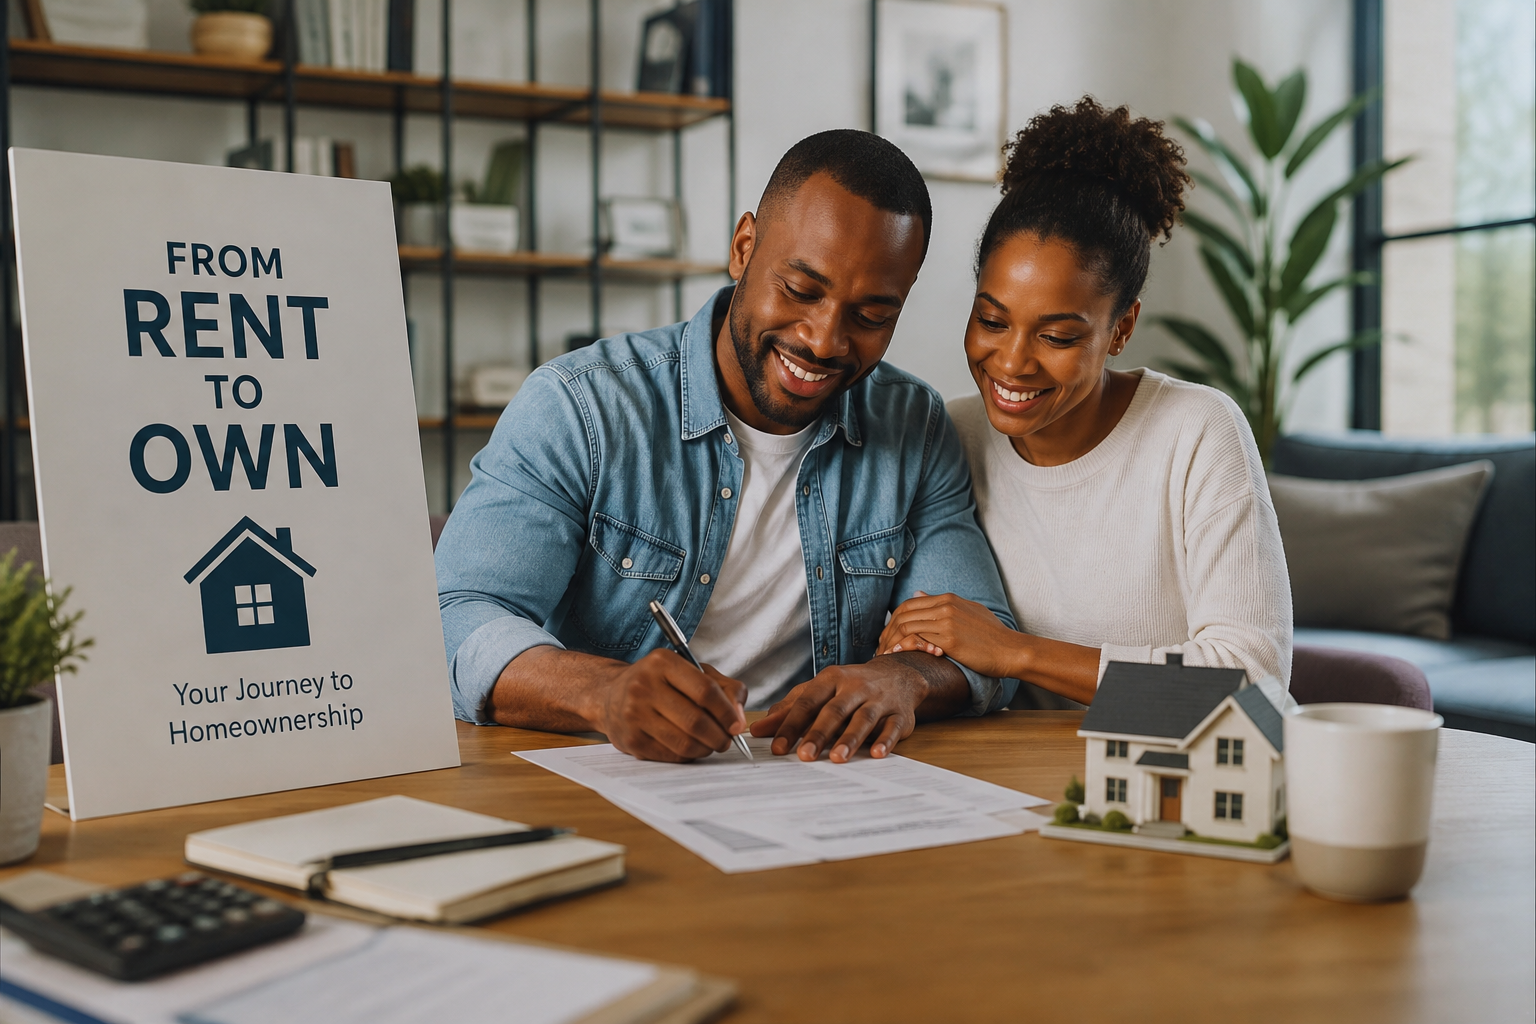
In a traditional rent-to-own arrangement, a person occupies a property while making regular payments under an agreement that provides an eventual path to ownership.
However, buyers should understand that rent-to-own is not the same as simply renting a house.
The agreement should clearly explain:
The purchase price
The monthly payment
How much of the payment contributes towards ownership
The length of the agreement
When ownership transfers
What happens if payments are missed
Maintenance and service-charge responsibilities
What happens if the buyer wants to exit
The legal structure can vary significantly between developers and providers, so buyers should always have the agreement reviewed before committing.
The wider trend is bigger than rent-to-own itself.
Private developers are increasingly using payment plans as a way of making their properties accessible to a broader range of buyers.
For example, a developer may offer a buyer a 20% deposit followed by instalments over 12, 24 or 36 months, depending on the project and agreement.
For a buyer, this can be easier to manage than raising the entire amount at once.
For a developer, flexible payment plans can also help attract buyers earlier in the development cycle and provide a more predictable sales pipeline.
First-time buyers often face a difficult choice. They can continue renting while saving for a deposit, but property prices may increase during that period.
Alternatively, they can purchase earlier and spread their payments over time. This creates an important financial question:
Is it better to continue paying rent while saving, or start putting that money towards an asset you intend to own?
There is no universal answer. The right choice depends on the property’s price, location, payment terms, rental cost, financing costs and the buyer’s income stability. But the growing availability of flexible payment options gives buyers more choices than the traditional “cash or mortgage” model.
The modern property buyer is becoming more financially conscious. Buyers increasingly want to understand not only the price of a property but also how they can realistically pay for it. This is encouraging developers to think beyond simply advertising a selling price.
A property marketed at KSh10 million may attract limited interest if the buyer needs to produce several million shillings immediately. The same property may become more accessible if the developer offers a structured payment plan that matches the buyer’s income and financial timeline. This is particularly relevant for buyers purchasing property while it is still under construction.
Flexible payment terms should never be the only reason to buy a property. A convenient payment plan cannot compensate for poor location, weak rental demand or an unreliable developer. Before committing, buyers should consider:
These questions can protect buyers from focusing too heavily on an attractive monthly payment while overlooking the bigger financial picture.
It may become an increasingly important part of the market, but it is unlikely to replace traditional mortgages or cash purchases. Instead, Kenya’s property market is likely to offer more ways to become a homeowner. Some buyers will continue to use mortgages while others will purchase properties entirely in cash. Some will buy during construction using developer payment plans, and others may explore genuine rent-to-own or tenant-purchase arrangements. The common theme is flexibility.
The traditional idea of buying a home save for years, raise a large deposit, take a mortgage and then repay it over a long period is no longer the only path available to buyers. Private developers are increasingly experimenting with payment structures that allow buyers to spread the cost of a property over time. For buyers, this can make homeownership feel more achievable.
But flexibility should never replace due diligence. Before signing any agreement, understand the total cost, payment schedule, ownership structure, legal obligations and exit terms. The future of homeownership in Kenya may not simply be about whether people can afford to buy a home today. It may increasingly be about whether the real estate industry can create smarter and more flexible ways for people to own one tomorrow.
Talk to our experts or Browse through more properties.